TELFORD, PA, October 1, 2026
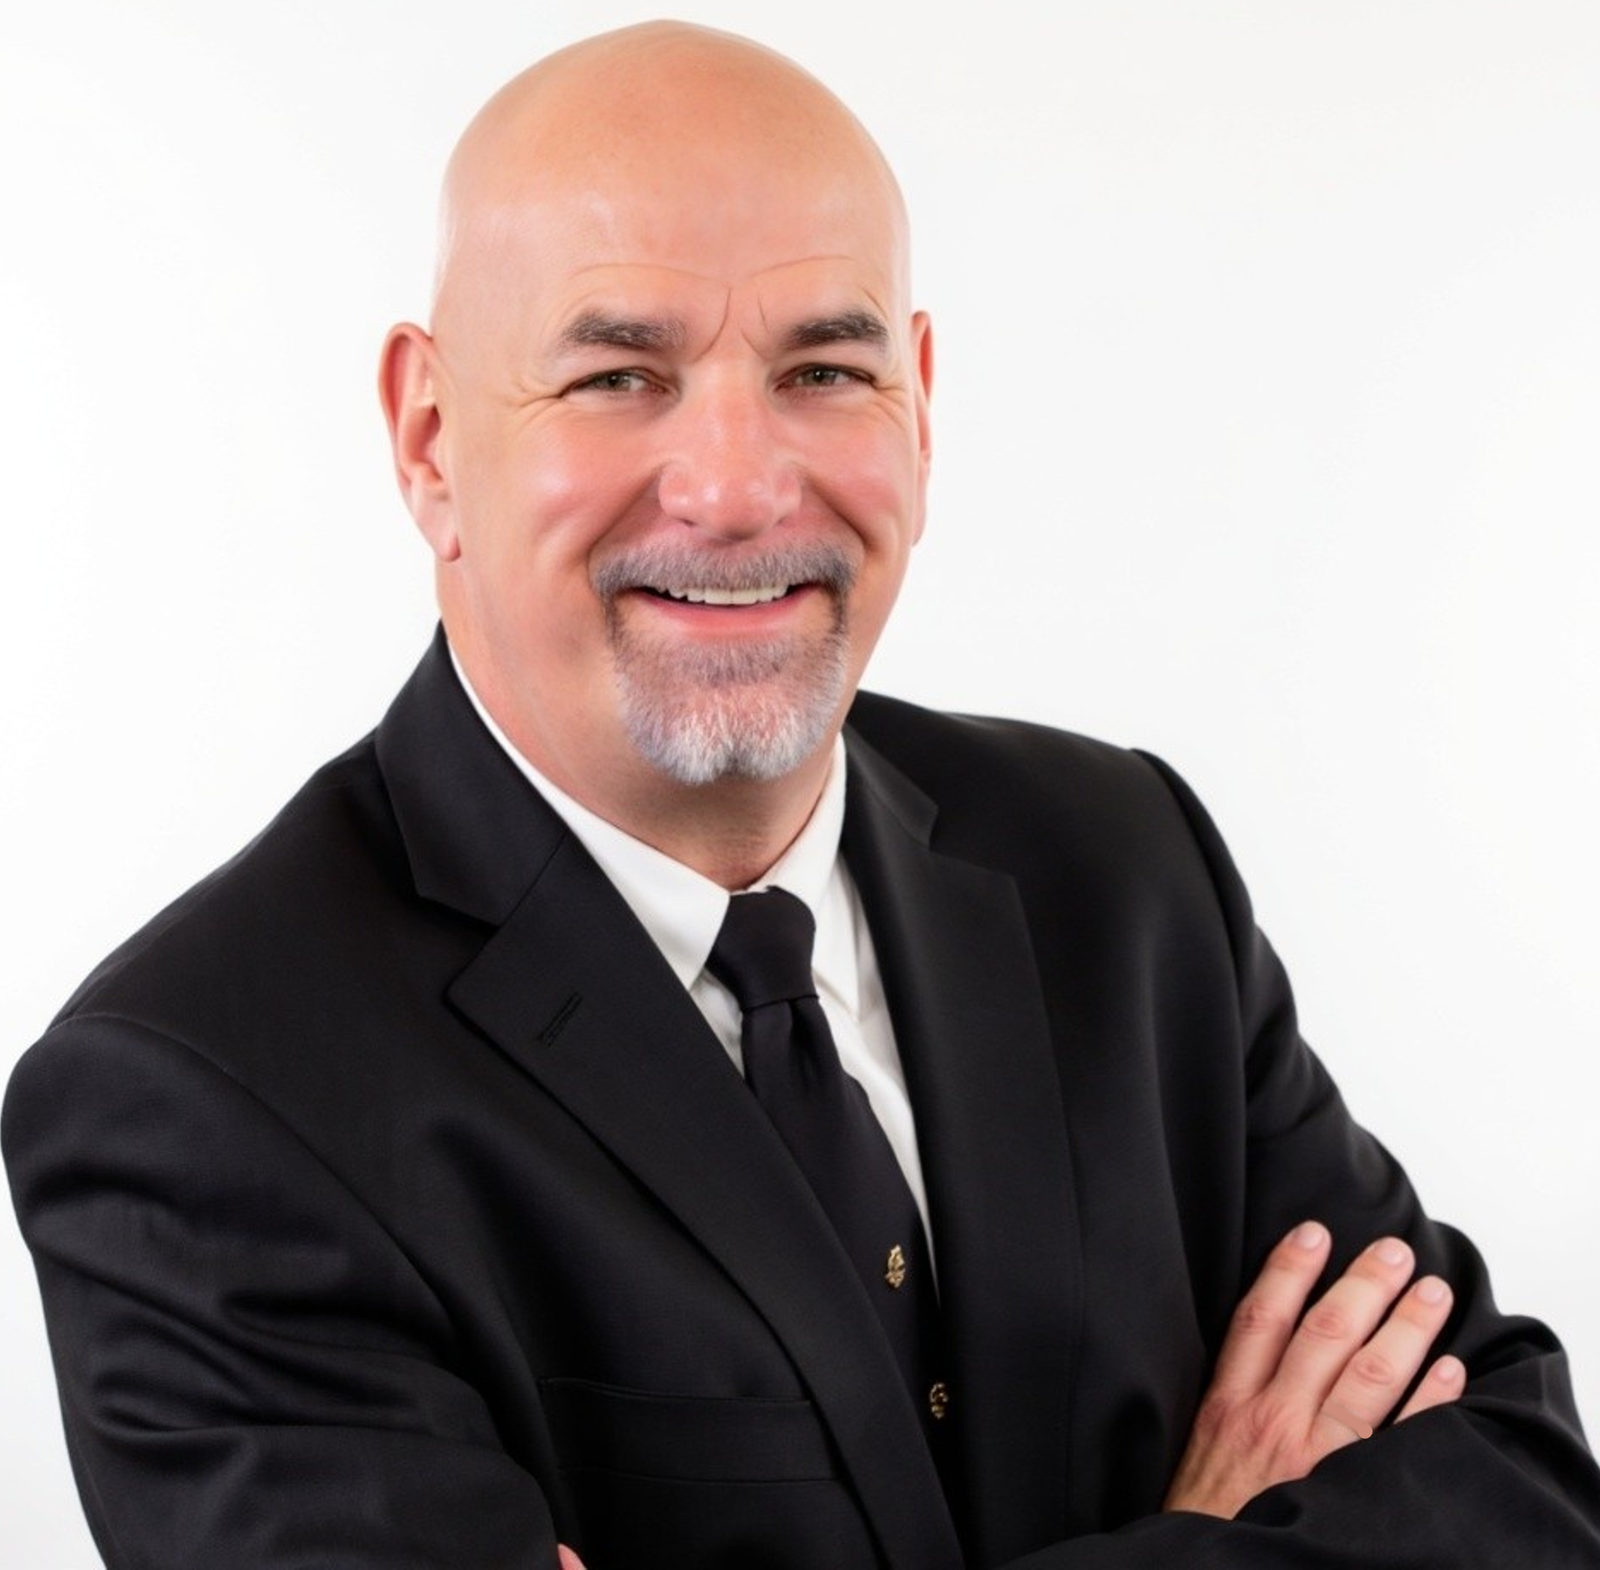
George McReynolds discussing healthcare and long-term care
Listen to the interview on the Business Innovators Radio Network: https://businessinnovatorsradio.com/interview-with-george-mcreynolds-founder-of-mcreynolds-company-discussing-healthcare-and-long-term-care/
In this episode of Influential Entrepreneurs, Mike Saunders, the Authority Positioning Coach, had the pleasure of welcoming back George McReynolds, the founder of McReynolds & Company. Delved into the critical topic of healthcare and long-term care, particularly focusing on the financial traps that can ensnare those planning for retirement.
Planning Healthcare Costs Before Retirement
Retirement is often viewed as a long-awaited milestone, a time to relax and enjoy life after years of hard work. However, for many, the prospect of retiring early—before the age of 65 when Medicare eligibility begins—can lead to significant financial challenges, particularly regarding healthcare costs. As highlighted in a recent podcast episode featuring George McReynolds, founder of McReynolds & Company, it is crucial to plan for healthcare expenses well before retirement to avoid falling into financial traps that can jeopardize one’s financial security.
Understanding the Healthcare Landscape.
The healthcare landscape in the United States is complex and often daunting for those approaching retirement. For many individuals, especially those in professions such as first responders who may not have paid into Social Security or Medicare, retiring early can lead to a lack of coverage. McReynolds notes that many people mistakenly assume that COBRA, which allows individuals to continue their employer-sponsored health insurance for a limited time, will suffice. However, COBRA coverage is typically limited to 18 months and can be prohibitively expensive, costing individuals 102% of what their employer was previously paying.
This misconception can be particularly detrimental for those who retire at a younger age, such as 50 or 55, leaving them to cover healthcare costs for a decade or more before Medicare kicks in. The financial burden of these expenses can lead to unexpected hardships, including the need to return to work or drastically alter retirement plans.
The Rising Costs of Healthcare
As the population ages, the costs associated with healthcare are only expected to rise. McReynolds points out that approximately 12,000 individuals turn 65 every day, a trend that will continue for several years. This demographic shift means that the demand for healthcare services will increase, leading to higher costs. For instance, Medicare premiums for Part B and Part D saw a 9.7% increase from 2025 to 2026, and this trend of rising costs is likely to persist.
Moreover, individuals need to be aware that healthcare needs change significantly as people age. While younger individuals may primarily face health issues related to accidents, older adults often contend with chronic conditions that require ongoing treatment and care. McReynolds emphasizes that the probability of needing long-term care by age 65 is a staggering 70%. This statistic underscores the importance of planning for healthcare expenses as part of retirement strategy.
The Interplay Between Health and Wealth
The relationship between health and financial stability cannot be overstated. McReynolds asserts that “you cannot keep your health if you can’t keep your wealth,” highlighting the precarious balance many individuals face when medical expenses arise. A staggering 60% of bankruptcies in the United States are linked to medical expenses, often incurred despite having insurance at the time of illness. The loss of employment, which frequently accompanies health crises, can lead to the loss of health insurance, exacerbating the financial strain.
This reality emphasizes the need for proactive planning. Individuals must consider not only their immediate healthcare needs but also the potential long-term implications of aging and health deterioration. This includes exploring options such as long-term care insurance, health savings accounts, and other financial products designed to mitigate healthcare costs in retirement.
George shared: “if they actually retired and didn’t go to work anymore, they didn’t have enough quarters to go into Medicare for Medicare Part A. So, that’s something a lot of times people, when they retire early before Medicare, they think that that COBRA will cover them. But COBRA is only for 18 months. Yep. And it’s very expensive.“
In conclusion, planning for healthcare costs before retirement is not merely a financial consideration; it is a crucial component of ensuring a secure and fulfilling retirement. The complexities of the healthcare system, coupled with the rising costs associated with aging, necessitate careful planning and informed decision-making. As George McReynolds advises, individuals must educate themselves about their healthcare options, consider the long-term implications of their retirement decisions, and seek out professional guidance to navigate the intricacies of healthcare planning. By doing so, they can avoid falling into the traps that many before them have faced, ensuring that their retirement years are not overshadowed by financial burdens related to healthcare.