ROSEVILLE, CA, October 8, 2026
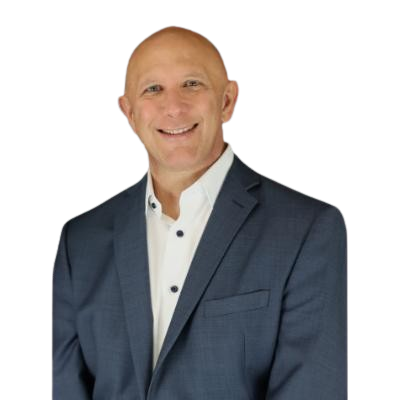
Terry Wheeler discussing the retirement income blind spot
Listen to the interview on the Business Innovators Radio Network: https://businessinnovatorsradio.com/interview-with-terry-wheeler-founder-ceo-of-we-alliance-wealth-advisors-discussing-the-retirement-income-blind-spot/
In this episode of Influential Entrepreneurs, Mike Saunders had the pleasure of welcoming back Terry Wheeler, the founder and CEO of WE Alliance Wealth Advisors and SWLA. They delved into the critical topic of the retirement income blind spot, a subject that many overlook until it’s too late.
Identify and Close Retirement Income Gaps
On the journey to retirement, individuals often face a critical challenge: ensuring their retirement savings will support their desired lifestyle. A “retirement income gap” occurs when a discrepancy exists between the income needed to maintain a comfortable standard of living and the income projected to be available from various sources. Understanding and addressing this gap is essential for a secure and fulfilling retirement.
Understanding Retirement Income Needs
The first step in identifying a retirement income gap is to understand your financial needs clearly. This involves assessing the essential expenses that will persist throughout retirement, as well as the discretionary spending that may fluctuate over time. As Terry Wheeler, founder and CEO of WE Alliance Wealth Advisors, points out, retirees must evaluate what they need, want, and wish for in retirement. This assessment should include essential living expenses, healthcare costs, travel, and leisure activities that support overall quality of life.
To facilitate this process, retirees can utilize various formulas and rules of thumb to estimate their income needs. However, these figures often need adjustment for inflation, a common oversight. For instance, a retiree may calculate that they need $15,000 per month, but failing to account for inflation could mean that, in 15 years, this amount may need to double or even triple to maintain the same standard of living. Thus, stress-testing portfolios against inflation is vital to accurately forecasting future income needs.
Evaluating Income Sources
Once retirees have a clearer picture of their income needs, the next step is to evaluate the income sources available to them. This typically includes Social Security benefits, pensions, and personal savings or investment portfolios. Each source has its own characteristics and limitations. For example, Social Security provides a stable, inflation-adjusted income stream, while pensions may vary significantly based on employment history and the specific employer’s offerings.
Wheeler emphasizes the importance of securing a “base level of income” that retirees cannot outlive. Retirees can achieve this through careful portfolio design or private pensions that guarantee consistent cash flow. Addressing this foundational income is crucial because it lets retirees focus on enjoying their “go-go years”—the early retirement phase when individuals are often more active and engaged in travel and leisure activities.
Identifying the Gap
With a clear understanding of income needs and available sources, retirees can identify any gaps. This is where the distinction between desired income and projected income becomes critical. If Social Security and pensions fall short of the necessary monthly cash flow, retirees face a gap they must address.
Common mistakes retirees make in this phase include underestimating future expenses, failing to account for variable income needs throughout retirement, and not having a clear strategy for converting lump-sum investments into consistent cash flow. Many individuals approach retirement focused on total portfolio value, neglecting the importance of cash flow management.
Closing the Gap
Closing the retirement income gap requires a proactive approach. Retirees should consider several strategies to boost their income. This may include:
- Adjusting Investment Strategies: Transitioning from accumulation strategies to growth with defense plus income-focused strategies is essential. This often involves reallocating investments to generate more reliable income streams, such as dividend-paying stocks, bonds, or annuities.
- Creating a Withdrawal Strategy: A systematic withdrawal plan can help manage the depletion of retirement savings while ensuring income needs are met. This plan should be flexible enough to adapt to changing circumstances, such as market fluctuations or unexpected expenses.
- Reassessing Lifestyle Choices: In some cases, retirees may need to adjust their lifestyle expectations either up or down to align with their financial reality. This might involve downsizing, relocating to a more affordable area, or reassessing discretionary spending. Wheeler states that many of his clients are so good at delayed gratification that they actually have to learn to spend more and enjoy the retirement they worked so hard to build.