TELFORD, PA September 30, 2026
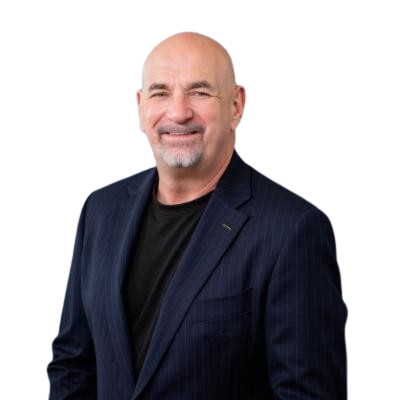
George McReynolds discussing the longevity trap
Listen to the interview on the Business Innovators Radio Network: https://businessinnovatorsradio.com/interview-with-george-mcreynolds-founder-of-mcreynolds-company-discussing-the-longevity-trap/
In this episode of Influential Entrepreneurs, the host had the pleasure of speaking with George McReynolds, founder of McReynolds and Company. The conversation delved into the intriguing topics of the longevity trap and the taxes jaw, exploring how these issues can significantly impact retirement planning.
Plan for Longevity, Not Average
In recent years, advancements in healthcare and lifestyle choices have led to increased life expectancy, with many individuals now living well into their 80s and 90s. While this is undoubtedly a positive development, it brings forth unique challenges that can strain retirement finances. The concept of the “longevity trap” serves as a crucial reminder of the importance of thorough financial planning and proactive measures to mitigate the risks associated with an extended lifespan. By understanding the potential financial implications of longevity and taking steps to prepare, retirees can navigate this complex landscape and enjoy their golden years with greater confidence and security.
The average life expectancy at birth in the United States is approximately 78 years. However, this figure can be misleading, particularly for those who reach the age of 65, as they have a 50% chance of living to age 90. This discrepancy highlights the need for individuals to plan for the possibility of living longer than average rather than merely relying on statistical norms. Many people fall into the trap of planning for an average lifespan, which can lead to financial shortfalls in later years. This is where the longevity trap becomes evident: it is not the length of life itself that poses a challenge, but the failure to prepare adequately for those extra years.
As the podcast emphasizes, the risks associated with retirement compound over time. Factors such as inflation, healthcare costs, and taxes can significantly erode savings if not accounted for in a comprehensive financial plan. For instance, individuals who are overly conservative in their spending habits may find themselves scrimping and saving throughout their retirement, living a life of deprivation while failing to enjoy the fruits of their labor. This mindset often stems from a lack of clarity regarding their financial situation and future needs. The fear of outliving their savings can lead to a reluctance to spend, resulting in missed opportunities for travel, experiences, and meaningful connections with loved ones.
To combat this, it is essential for individuals to adopt a mindset that prioritizes longevity in their financial planning. A mentor in the podcast, Nick Murray, aptly states that the great goals of life emerge after answering the question: “Am I going to live longer than my money, or is my money going to live longer than me?” This perspective shift can be transformative, allowing individuals to focus on their goals and experiences rather than fixating solely on their financial resources. By establishing a tested financial plan that accounts for potential longevity, individuals can gain the confidence to spend money on enriching experiences, travel, and even philanthropy, thus creating a legacy that extends beyond mere financial inheritance.
The podcast also touches on the emotional aspect of financial planning for longevity. Many clients have expressed relief and joy upon realizing that their money is indeed sufficient to support a fulfilling life in retirement. The concept of “giving with warm hands” rather than “cold hands” encapsulates the idea of actively sharing resources and experiences with loved ones while still alive, fostering deeper connections and creating lasting memories. This proactive approach not only enhances the quality of life but also reinforces the notion that legacy is not merely about what one leaves behind but about the lives one touches along the way.
In conclusion, planning for longevity rather than average is crucial for ensuring a secure and fulfilling retirement. As life expectancy continues to rise, individuals must recognize the importance of comprehensive financial planning that anticipates the challenges of extended lifespans. By doing so, retirees can avoid the pitfalls of the longevity trap, embrace their financial freedom, and fully engage in the experiences that make life rich and meaningful. With thoughtful preparation, the golden years can be a time of exploration, connection, and joy—allowing individuals to truly live every day to its fullest.
George shared: “All of the great goals of life emerge after you answer the question. Am I going to live longer than my money? Or is my money going to live longer than me?